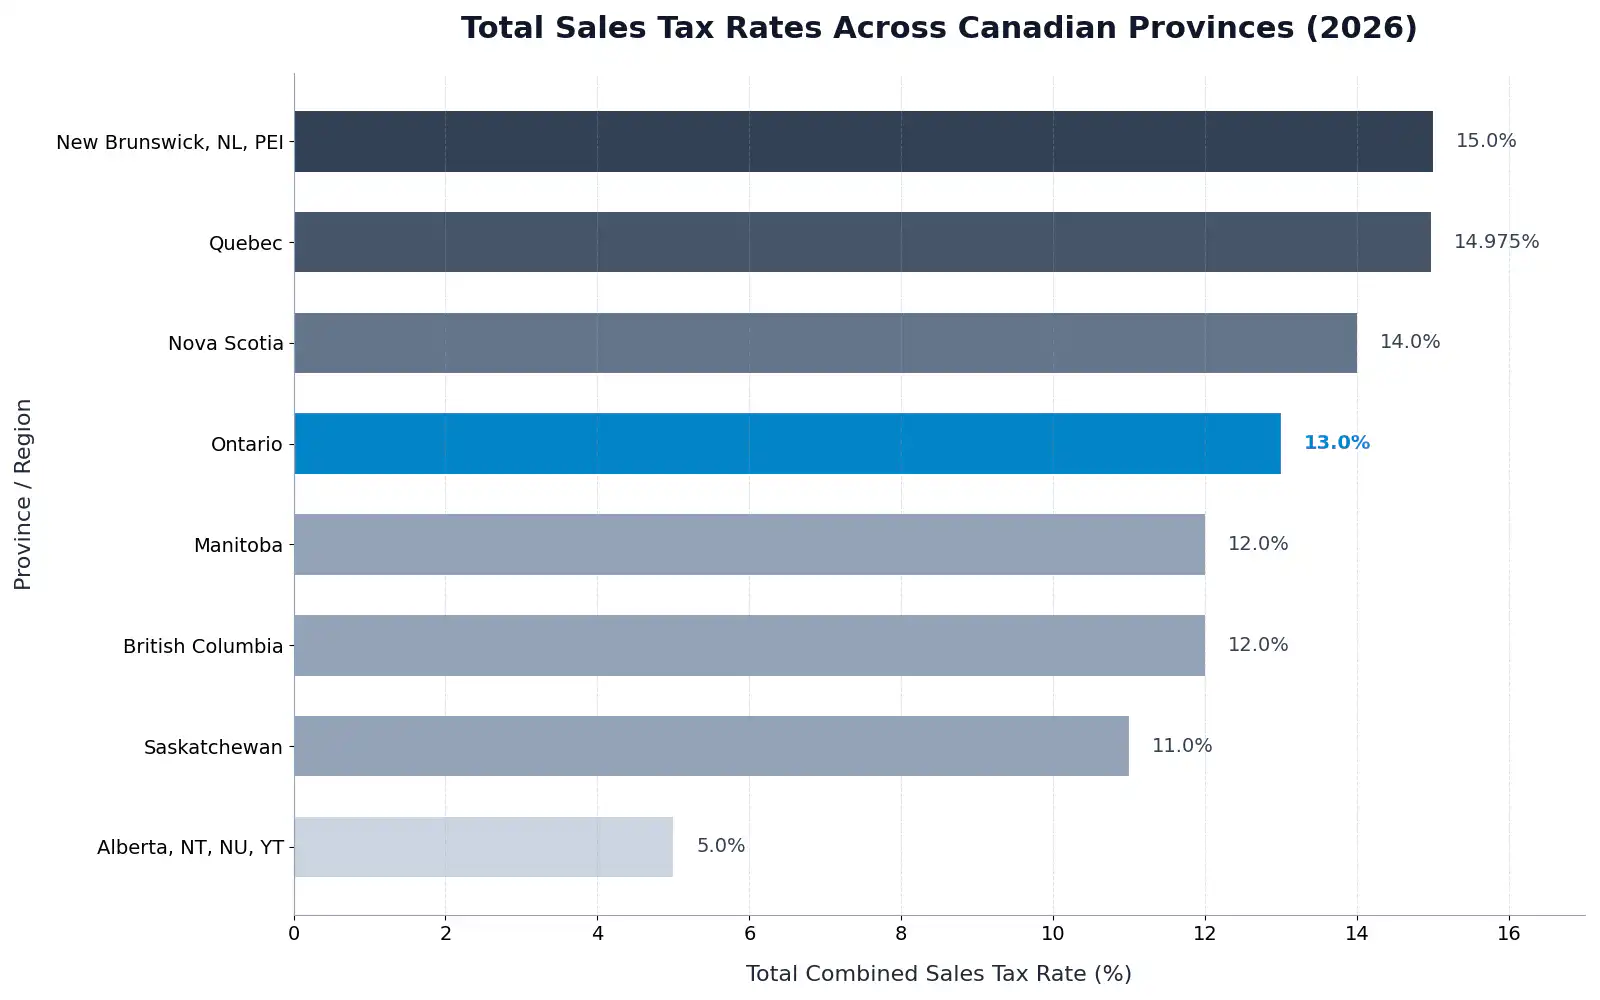
For a standard taxable sale in Ontario, the calculation uses 13.00% HST. Enter the price, then choose Add tax or Remove tax. The province is fixed to Ontario; amounts are in Canadian dollars. The CRA charging guide explains why the type and place of supply must be established before applying a rate.
Calculate a price or receipt
Amount before tax$100.00
HST 13%$13.00
Total with tax$113.00
Example for a standard-rated sale in Ontario. Only explicitly selected provincial taxes are included. JavaScript is needed to change the amount or tax applicability.
To add tax, enter the price before tax. To remove tax, enter the total that already includes the selected taxes. If you change a provincial-tax switch, use the rate that actually applied to the purchase. The result estimates tax arithmetic; it does not determine an exemption, a registration obligation, or eligibility for an input tax credit.
Add tax: the formula
- HST = price before tax × 0.13
- Total = price before tax + the applicable tax amounts.
For a $100 purchase, HST is $13.00, and the total is $113.00.
| Price before tax | HST | Total |
|---|---|---|
| $20.00 | $2.60 | $22.60 |
| $100.00 | $13.00 | $113.00 |
| $500.00 | $65.00 | $565.00 |
| $1,000.00 | $130.00 | $1,130.00 |
| $2,500.00 | $325.00 | $2,825.00 |
Remove tax from a total
If all the selected standard taxes were included, divide the total by 1.13 to estimate the price before tax. Multiply that unrounded base by each applicable rate to find the tax components. Do not subtract 13.00% directly from the total: that percentage was originally applied to a smaller, pre-tax amount.
For a receipt showing $1,130.00, the unrounded base is $1,000.00. HST is $130.00. Compare the result with the supplier’s actual invoice. Separately rounded lines or tax components can cause a one-cent difference when reversing a rounded total.
What this province setting does
Ontario uses one combined 13% HST rate on a standard taxable sale. Do not add a separate 5% GST to that HST. A qualifying provincial point-of-sale rebate can change the amount collected; the standard-rate calculator does not determine eligibility for that relief.
Check the transaction before using the result
A seller’s head-office address does not by itself determine GST/HST. Delivery, the customer address associated with a service, the nature of the supply, and special rules can matter. Start with CRA’s place-of-supply guidance. A zero-rated or exempt supply does not use the standard rate in the examples above.
This is a sales-tax calculator, not an income-tax calculator or a GST/HST return. For business registration, see the GST/HST registration guide. For filing, use the return workflow.
For the broader provincial rules, see the Ontario sales-tax guide.