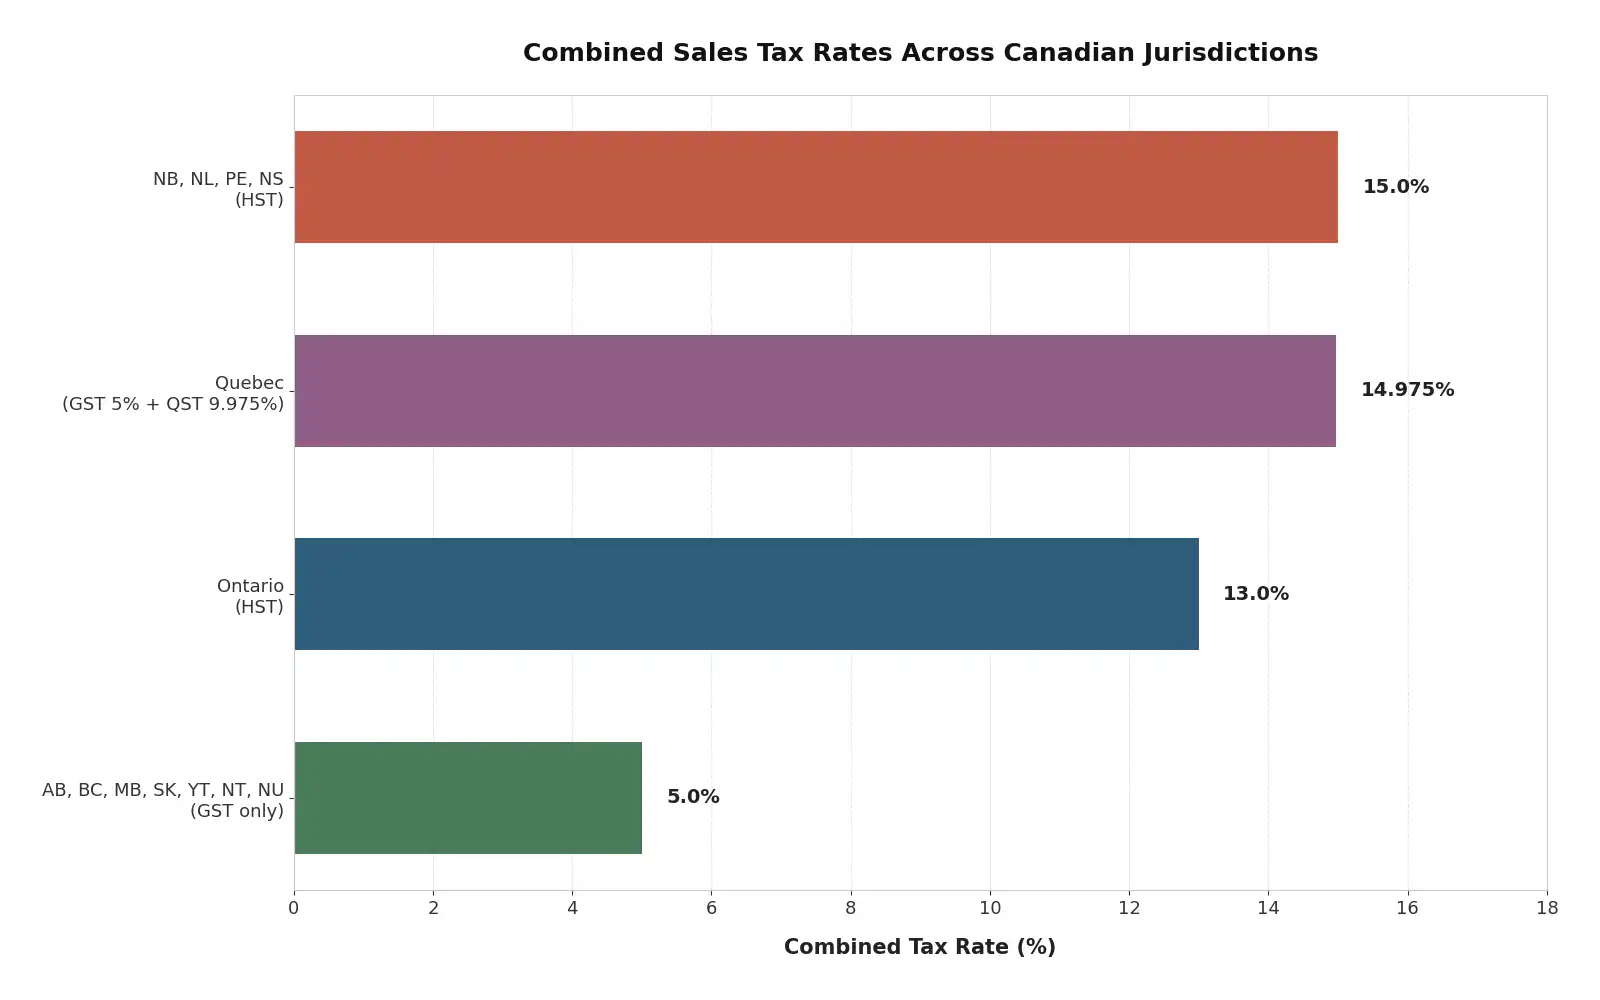
RC4022 is the CRA’s general guide for businesses that are registered, or may need to register, for GST/HST. It is a guide, not a form to file. It covers the ordinary workflow: registration, charging and collecting tax, input tax credits (ITCs), GST/HST returns, and selected real-property topics. CRA: RC4022 publication page
Use the current online version
Start with the CRA’s RC4022 publication page. It links to the online guide and PDF, so the reader can check the current revision before acting. CRA describes the guide as plain-language information and says it does not replace the law. RC4022 online guide
The guide is useful when a business needs to understand its next task rather than merely calculate a rate:
| Question | Where RC4022 helps |
|---|---|
| Do I need to register? | The small-supplier rule and common registration exceptions |
| What do I charge? | GST/HST and place-of-supply guidance, with links for details |
| Can I recover tax on an expense? | ITC eligibility, commercial-use limits, and documentation |
| What must I report? | Return preparation, reporting periods, and regular versus quick-method context |
Important limits of this guide
RC4022 identifies situations that need specialized guidance. CRA says it does not provide detailed guidance for selected listed financial institutions, non-residents and certain businesses such as tour operators, builders and land developers, or the digital-economy regimes. It also notes that Quebec generally administers GST/HST for businesses physically located in Quebec. Use the relevant specialized CRA or Revenu Québec material when one of those facts applies. RC4022 scope and exclusions
A practical way to read RC4022
- Confirm whether the business is registered, required to register, or considering voluntary registration.
- Read the section for the immediate job—registration, collection, ITCs, or filing—rather than treating the guide as a completed return.
- Follow the linked CRA page when the result depends on a specific province, supply type, industry, or reporting method.
- Retain invoices and records before claiming an ITC; commercial use and required supporting information matter.
For a registration walkthrough, see GST/HST registration in Canada. For filing a return, see GST/HST filing guidance.